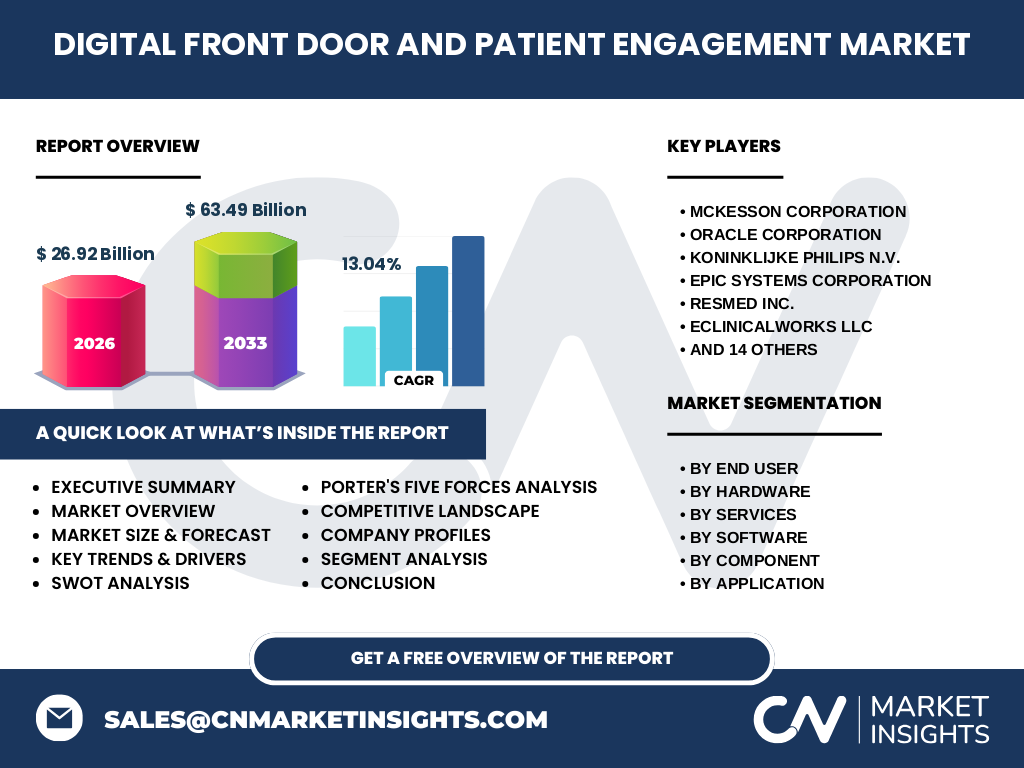
Market overview of the Digital Front Door And Patient Engagement Market
Our analysis indicates the Digital Front Door And Patient Engagement Market reaches a valuation of 26.92 Billion by 2026. This ecosystem encompasses patient intake and registration software, biometric authentication devices, and telehealth communication platforms. These technologies are regulated by bodies like the FDA and HIPAA, ensuring data privacy and secure patient interactions across payer and provider networks.
What are the primary growth drivers and market restraints?
Structural growth drivers include rising demand for chronic disease management and virtual care adoption. However, our research highlights stringent cybersecurity compliance and integration hurdles with legacy electronic health record systems as core restraints. Industry innovators must navigate strict regulatory frameworks enforced by the ONC and HHS to maintain interoperability.
Emerging trends and technology adoption patterns
The shift toward Conversational AI and Automated Care Navigation is transforming patient workflows. Companies like Hyro AI Inc. and Orbita Inc. lead this space by deploying natural language processing tools for appointment scheduling software, reducing administrative friction for individual users and major hospital systems alike.
COVID-19 impact analysis and recovery trajectory
The pandemic permanently accelerated telemedicine adoption, forcing providers to rapidly deploy cloud hosting services and remote patient monitoring devices. Recovery trajectories show sustained double-digit expansion as healthcare institutions prioritize resilient digital intake workflows to mitigate future operational disruptions and staffing shortages.
Competitive benchmarking and strategic positioning
The market features high vendor fragmentation alongside dominant enterprise consolidators. Industry giants like Oracle Corporation and Epic Systems Corporation integrate deep EHR functionalities, while specialized players such as Luma Health Inc. and Artera Technologies Inc. focus on agile patient communication software and rapid deployment.
Executive summary of the Digital Front Door And Patient Engagement Market
Based on our research, the Digital Front Door And Patient Engagement Market is positioned for explosive acceleration, surging from 26.92 Billion in 2026 to 63.49 Billion by 2033. This trajectory represents a robust 13.04% CAGR, driven by digital transformation mandates across provider networks and payers.
Market forecast from 2027 to 2033
Projections confirm that the sector will expand at a 13.04% CAGR, culminating in a market size of 63.49 Billion by 2033. This growth is heavily supported by increased venture capital funding and heightened consumer expectations for consumer-grade healthcare interactions delivered via web-based and cloud-based delivery modes.
Segmentation analysis across hardware, software, and services
The market segments into hardware (biometric authentication devices, interactive kiosks), software (patient portal software, telehealth software), and services (cloud hosting, consulting). Software solutions command the highest share due to rapid demand for digital intake and registration tools managed by firms like Simple Interact LLC.
Geographic distribution and regional market analysis
Regional performance is led by North America, supported by robust health IT infrastructure and favorable reimbursement policies. Meanwhile, the Asia-Pacific region demonstrates the fastest growth trajectory, driven by massive investments in digital infrastructure, smartphone penetration, and government-led health modernization initiatives.
In-depth regional review of high-growth territories
North America dominates revenue generation, anchored by stringent regulatory mandates like the 21st Century Cures Act. Conversely, European markets exhibit steady adoption focused heavily on data sovereignty and cross-border interoperability standards overseen by regional health ministries and GDPR compliance frameworks.
Company profiles of key market participants
Leading ecosystem participants include McKesson Corporation, Koninklijke Philips N.V., and ResMed Inc., which leverage expansive distribution channels. Meanwhile, specialized innovators like SONIFI Health Incorporated and Solutionreach Inc. target niche engagement workflows to secure competitive differentiation in crowded provider markets.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is intense due to low switching costs for point solutions, though enterprise EHR vendors create high moats. Threat of substitutes remains moderate, while buyer bargaining power is high, forcing vendors like Carenet Health LLC and CareCloud Inc. to continuously enhance implementation and integration services.
SWOT analysis of the industry landscape
Strengths include high demand for remote patient monitoring devices. Weaknesses involve data privacy vulnerabilities. Opportunities lie in artificial intelligence integration for mental health applications. Threats center on evolving federal compliance mandates and interoperability friction managed by actors like Medical Information Technology Inc. and Veradigm LLC.
Value chain analysis from technology development to end-users
The value chain flows from foundational cloud hosting and software development to system integrators, ultimately serving providers, payers, and individual users. Companies controlling the middleware tier—such as Computer Programs and Systems Inc. (CPSI) and eClinicalWorks LLC—capture significant value by bridging disparate data silos.
Investment insights and high-potential areas
Investors should focus on scalable cloud-based care navigation software and chronic disease management platforms. High-potential opportunities exist in funding startups that offer seamless interoperability with legacy systems, minimizing friction for providers utilizing platforms from American Well Corporation and Notable Health Inc.
Conclusion and strategic takeaways
Achieving market leadership requires robust cloud infrastructure, strict adherence to healthcare compliance, and advanced AI capabilities. With the market reaching 63.49 Billion by 2033, stakeholders must prioritize user-centric design to capture sustained demand across individual users, payers, and institutional providers.
Research methodology and data triangulation
Our baseline estimates are derived by triangulating primary stakeholder interviews with C-suite health IT executives, secondary macroeconomic indicators, and trade registry data from organizations like the HIMSS. This multi-tiered approach ensures accurate sizing of hardware, software, and services revenue streams.
Scope of the report and coverage parameters
This report covers the global Digital Front Door And Patient Engagement Market across multiple delivery modes, end-user verticals, and therapeutic outlooks including mental health and fitness. Limitations include exclusion of proprietary internal hospital expenditures not captured by public regulatory filings or commercial databases.
Recent developments and strategic industry announcements
Recent strategic moves feature aggressive merger and acquisition activity alongside AI product launches. Firms are forging partnerships to integrate automated chatbots and remote monitoring tools directly into enterprise workflows, reflecting a broader industry push toward proactive, consumer-driven healthcare delivery models.